Apartment buildings, 5 units and up

We buy Florida apartment buildings, on your terms.

Sell your apartment building in Florida, five units or five hundred. We can pay cash, buy on seller financing you set, or take over your existing loan where the loan and the lender allow it. You see the options side by side, in writing.

An insurance renewal that jumped, a loan coming due, a roof the reserves cannot cover, partners who want out. Selling a building full of tenants is not like selling a house.

Prefer to text? Text (305) 914-4191 · Lea esta página en español

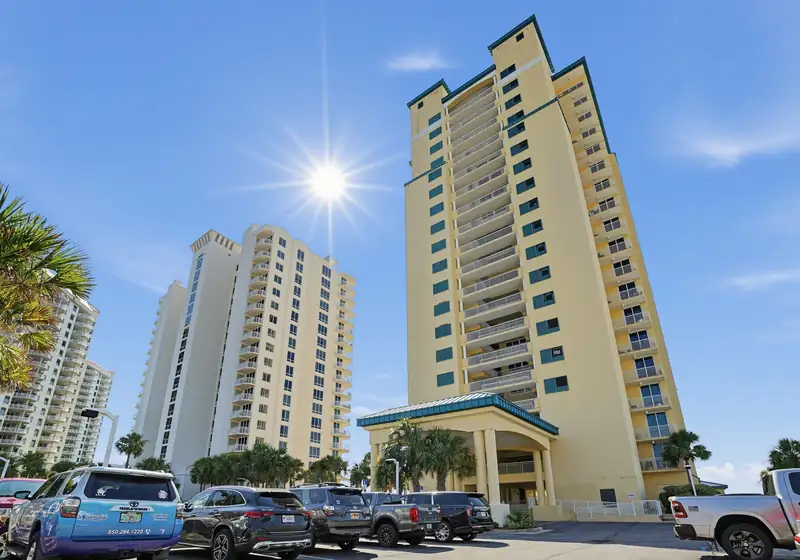
Multi-story residential towers in Navarre Beach, Florida
Residential towers in Navarre Beach, Florida
5 units and upNo size limit, anywhere in Florida
Tenants in placeNo need to empty a single unit
Licensed title companiesEvery closing goes through one
No cost to askNo obligation, no pressure

How we help apartment owners

Your building, your timeline, your call.

Florida apartment insurance, Trepp data
+42.1%
Median yearly change in insurance cost for securitized Florida multifamily properties in 2023
+16.0%Rest of the U.S., 2023
−6.2%Florida, 2025, from a higher base

HOMKEYS LLC is a Florida company that buys houses, condos, mobile homes, land, and now multifamily property with five or more units, with no size limit. Dor Tzadok leads HOMKEYS and oversees every offer and closing.

An apartment building is priced on its income, not on the houses down the street. We start with your rent roll and last 12 months of income and expenses, see the building, then put the options in writing with your net on each. You can also compare them with a listing through a commercial real estate broker.

From our files

What we have done, said plainly
Aerial view of a golf and lake community in Southwest Florida
A Southwest Florida community from the air
The deals in our files are houses, not apartment buildings. But they use the same structures we offer apartment owners. In Port Charlotte this fall we bought a house subject to the sellers’ loan: the loan stayed in place, the sellers got cash at closing and paid none of the closing costs. In Lake Wales we bought a package of seller-financed homes, so we know a carried note from the buyer’s side. We have also bought for cash in Pace and Winter Haven.

Real HOMKEYS residential deals. Names, addresses and prices left out to protect the sellers’ privacy.

Who sells to us

Why Florida owners sell apartment buildings

01

Tired landlords

Years of late-night calls and turnovers. Seller financing can keep the income and drop the work.

02

Inherited buildings

A building now owned by several heirs. Probate may come first; a Florida probate attorney can say which process fits. See selling inherited property.

03

Partners splitting up

One partner wants cash, another wants income. Part cash and part note can work, if your LLC or partnership agreement allows it.

04

A balloon coming due

When a loan’s term is shorter than its amortization, the remaining balance comes due at maturity. If a refinance does not work, a planned sale beats a rushed one.

Source
05

Costs rising faster than rents

Insurance, taxes and repairs eat the margin. Facing a new roof or plumbing, many owners sell before they spend.

06

Planning the next step

Retiring, a 1031 exchange, or wanting income instead of a building.

Three ways to sell

Most buyers give you one number. We show you three ways.

Option 1

Cash sale, as is

Best for
A firm date and a clean exit, even with vacancies or repairs
What it needs
Rent roll, 12 months of income and expenses, a look at the building
Trade-off
The price reflects repairs, vacancy and a buyer’s cost of money
Option 2

Seller financing

Best for
Paid-off or low-debt buildings, when you want a higher price and monthly income
How
You set the price, down payment, rate and term. We pay you monthly, secured by a recorded mortgage on the building.
What it needs
Equity to carry the note, and a Florida attorney to draft the papers
Option 3

Taking over your loan

Best for
A good-rate loan that would cost a lot to pay off early
How
Only where the loan documents and the lender allow it, usually through the lender’s assumption process.
What it needs
The lender’s approval of HOMKEYS as borrower, and its fees

You can also compare our written options with a listing through a commercial real estate broker. Read more on the cash sale, how a subject-to sale works for houses and comparing your options. Subject to qualification, property inspection, and transaction terms. HOMKEYS does not give legal or tax advice.

Five units and up

Why five units changes the sale

Lenders treat one to four units as residential and five or more as multifamily, financed with a commercial loan. Fannie Mae’s small loan program, for example, covers properties with 5 or more units and requires a debt service coverage ratio of at least 1.25: net income at least 1.25 times the loan payment.

That changes how a buyer values your building. Lenders weigh the income approach most: net operating income (income minus operating expenses, not the mortgage) divided by a market cap rate. The books drive the price, so clean records are worth money. Before you talk to any buyer, gather:

  • A current rent roll: unit, rent, deposit and lease dates
  • A trailing 12-month income and expense statement (T-12)
  • Signed leases that match the rent roll
  • Service contracts and vendor agreements
  • Insurance policy, premium history and tax bills
  • Loan documents and the latest statement

Sources: Fannie Mae term sheet · Rentometer · Regions agency loan checklist · DoorLoop checklist

Taking over a loan

What your loan papers probably say

Fannie Mae and Freddie Mac multifamily loans are generally assumable with the lender’s approval. Fannie Mae reviews the new borrower’s finances and experience. Freddie Mac conventional fixed-rate loans have carried a 1% assumption fee plus a processing fee. Not every agency loan moves: Freddie Mac’s value-add loans are not assumable.

Bank loans and loans packaged into commercial mortgage-backed securities (CMBS) are different. Many have a due-on-sale clause, which lets the lender call the loan if the building sells without its written approval, and federal law lets lenders enforce it. Many also carry a prepayment cost: yield maintenance, which pays the lender its lost interest, or defeasance, where the borrower buys government securities to replace the building as collateral.

So have a Florida real estate attorney read your loan documents first. We will never promise that a lender will agree. If the loan cannot move, we look at cash or seller financing.

Sources: Fannie Mae · Freddie Mac term sheet (Greystone) · Freddie Mac value-add (Lument) · 12 U.S.C. 1701j-3 · CommercialCafe on defeasance

Seller financing

How seller financing works on an apartment building

You act as the bank. HOMKEYS pays a down payment at closing and signs a note for the rest, and a mortgage on the building is recorded in your favor. You set the price, down payment, rate and term. Florida charges 35 cents per $100 in stamp tax on the note and 2 mills of intangible tax on the mortgage. Who pays them is negotiable.

Points for your tax professional, since we do not give tax advice. The IRS treats a sale with a payment after the year of sale as an installment sale, with gain generally reported as payments arrive. Depreciation recapture is reported in the year of sale, which matters on a building you have depreciated for years. Interest you collect is ordinary income.

Planning a 1031 exchange? Tell us early. An exchange generally needs a qualified intermediary and has 45-day and 180-day deadlines. Your adviser can say how a note fits.

Sources: Stamp and intangible tax · IRS Topic 705 · IRS like-kind exchanges · Schwab on 1031 timing

Estimate

What would seller financing pay you?

A rough illustration. Put in your own price and terms. Nothing is sent anywhere.

Amount you financeSale price minus the down payment
$0
Monthly payment to youPrincipal and interest, equal payments over the term
$0
Total you collectDown payment plus every monthly payment
Enter a price to compare

Illustration only, not an offer. It leaves out taxes, closing costs, any balloon date and the risk of a buyer default. Subject to qualification, property inspection, and transaction terms.

Florida apartment knowledge

What Florida apartment owners run into

01

Insurance

Trepp data on securitized Florida apartment properties shows median insurance costs up 17.3% in 2022 and 42.1% in 2023. They fell 6.2% in 2025, from a much higher base. A buyer prices your current premium.

Source
02

Property tax after a sale

Florida caps yearly increases in the assessed value of non-homestead property, apartment buildings included, at 10%, not counting school taxes. After a sale the cap resets to full market value the next January 1, so a buyer plans for a higher tax bill than yours.

Source 1 · Source 2 · Source 3
03

Hurricanes and flood zones

Check the building on FEMA’s flood maps. In high-risk A and V zones, loans from federally regulated lenders require flood insurance. Ask your insurance agent what limit fits the building.

Source 1 · Source 2 · Source 3
04

Milestone inspections are a condo law

Florida’s milestone inspection law, section 553.899 (from SB 4-D in 2022), covers condominium and cooperative buildings three stories or more. A rental building that is neither is outside it. Local rules can still apply: Miami-Dade recertifies most buildings at 30 years and every 10 years after.

Source 1 · Source 2
05

The Live Local Act

The Live Local Act lets developers build apartments on commercial, industrial or mixed-use land without a rezoning if at least 40% of units stay affordable for 30 years. Its tax break is for newly built developments with more than 70 affordable units, so most existing buildings do not qualify. An older building on commercial land may still interest a developer.

Source
06

Deferred maintenance

Roofs, plumbing, electrical, parking. A buyer’s lender usually orders a property condition assessment, and the price follows. We buy as is and show which repairs move our number.

Source

Tenants in place

Selling an apartment building with tenants

You do not need to empty a single unit. In Florida, a tenant’s lease does not end just because the landlord sells, unless the lease says so.

Security deposits and advance rent move with the building. Under section 83.49(7), the seller transfers them to the new owner with any earned interest and an accounting for each tenant, and a written receipt releases the seller. Tenant consent is not needed.

Section 83.50 requires the landlord to give tenants, in writing, a name and address for notices, and that person keeps the authority until tenants are told otherwise. So after closing, every tenant gets a letter with the new owner’s details.

Buyers often ask tenants to sign estoppel certificates confirming rent, deposit and lease dates. See also selling a house with tenants in Florida.

Sources: Florida Realtors legal library · Fla. Stat. 83.49 · Fla. Stat. 83.50 · Estoppel certificates

Florida apartment details

Numbers that come up when a building sells

Figures worth knowing before you sign. Confirm anything time-sensitive with your attorney or lender.

Deed stamps70 cents per $100. Miami-Dade: 60 cents plus a 45-cent surtax not waived for apartmentsSource ↗
Seller-financed note35 cents per $100 on the note, 2 mills on the mortgageSource ↗
Assessment cap10% a year on non-school taxes, reset after a saleSource ↗
Agency loan coverageFannie Mae small loans: 5+ units, minimum 1.25x debt service coverageSource ↗
Assumption fee1% plus a processing fee on Freddie Mac conventional fixed-rate loansSource ↗
Loans maturing in 202617%, or $875 billion, of U.S. commercial and multifamily mortgage balancesSource ↗

How it works

What we need to make an offer on your building

Send the address

Plus the unit count and county. Your broker or attorney can send it.

Share the books

Rent roll, T-12, leases and your latest loan statement.

We see the building

In person, or by Zoom or video call if you prefer.

Options in writing

Every option with your net on each. Close at a licensed title company on your date, 7 to 90 days out.

Real closings

Recent HOMKEYS closings in Florida

Each one closed at a licensed Florida title company. We show the city and month only, never the address, to protect the seller's privacy.

28 closings in 23 Florida cities and 17 counties since September 2024. See them on the map.

Questions

What Florida apartment owners ask us

What size apartment buildings do you buy?

Five or more units, anywhere in Florida, with no size limit: a 10-unit building or a large apartment complex. Send the address, unit count and county.

Can I sell my apartment building with tenants in it?

Yes. In Florida a lease does not end just because the landlord sells, unless it says so. Deposits and advance rent transfer to the new owner with an accounting under section 83.49(7).

Can you take over my existing loan?

Only where the loan documents and the lender allow it. Agency loans are generally assumable with lender approval and fees; many bank and CMBS loans are not. Have a Florida attorney review the loan.

How does seller financing work on an apartment building?

You set the price, down payment, rate and term. HOMKEYS signs a note, a mortgage is recorded in your favor, and you collect monthly payments. Ask your tax professional about installment sale reporting.

What do you need to make an offer?

The address and unit count, then the rent roll, a T-12, leases, service contracts, insurance and tax bills, and any loan statement. Then we see the building.

My building has vacancies and needs repairs. Will you still look?

Yes, we buy as is. Vacancy and repairs lower the price, and we show you by how much.

Should I list with a commercial broker instead?

You can compare. Our options come in writing with your net on each, so you or your broker can set them next to a listing.

How fast can you close, and what does it cost to ask?

Asking costs nothing and does not commit you. Closing is 7 to 90 days out, on your date, at a licensed Florida title company. On a cash sale, HOMKEYS pays the closing costs. A loan takeover follows the lender’s timeline.

More help

Guides for Florida property owners

Talking to other buyers too? Read how to spot a bad buyer in Florida before you sign anything.

Ready to compare your options? Start with the building.

About a minute. 4 short steps.

Dor Tzadok, CEO of HOMKEYS
Who you will talk toDor Tzadok, CEO, and the HOMKEYS team

Dor oversees every offer and closing. We explain every number, and we are glad to talk with your broker or attorney.

Find out what your Florida apartment building could do for you.

Send the address and unit count. We will come back with your options in writing.

Español